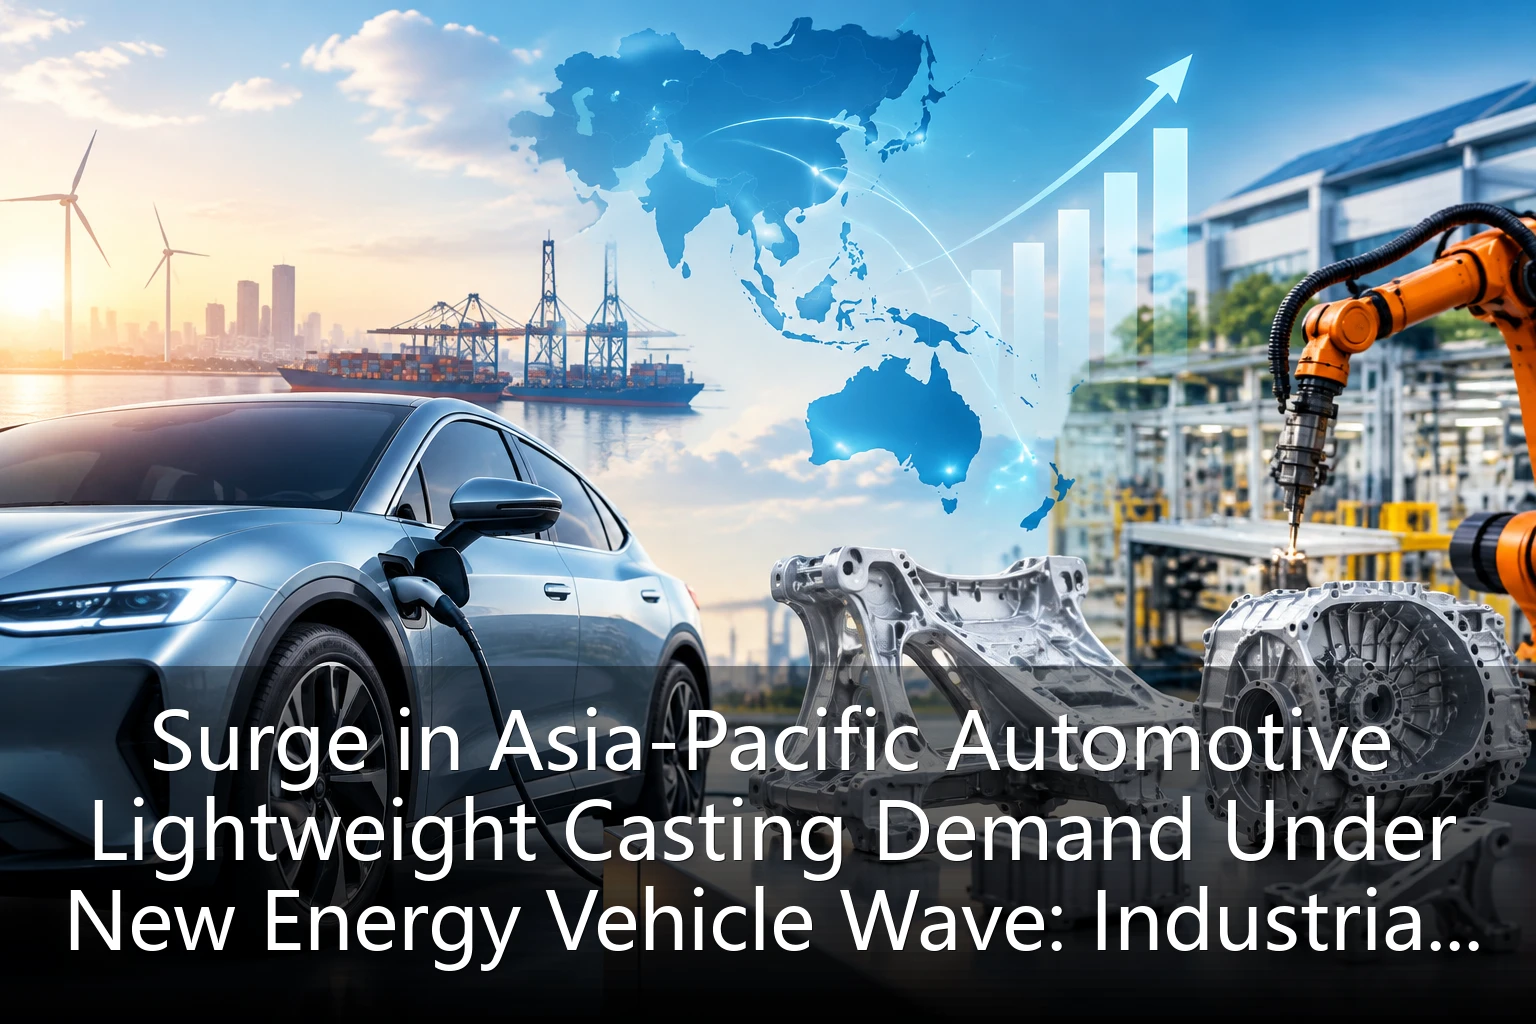
Driven by global carbon neutrality goals, the new energy vehicle industry is experiencing unprecedented development opportunities, and the automotive lightweight casting industry, as a core component manufacturing sector, has subsequently entered a period of rapid development. The Asia-Pacific region, as the world's largest automotive production and consumption market, is showing explosive growth in lightweight casting demand, with both industrial chain restructuring and investment opportunities coexisting.
Current Status and Growth Drivers of Asia-Pacific Automotive Lightweight Casting Market
According to the latest market analysis from OceanRing Asia-Pacific Finance, in the third quarter of 2026, the Asia-Pacific automotive lightweight casting market reached $87 billion, a year-on-year increase of 23.6%, and is expected to exceed $120 billion for the whole year. This growth is mainly driven by the dual factors of surging new energy vehicle production and the demand for lightweight transformation of traditional vehicles.
The popularization of new energy vehicles is the core driving force behind the growth of lightweight casting demand. Compared with traditional fuel vehicles, electric vehicles require lighter body structures to extend driving range while maintaining sufficient structural strength. In the Asia-Pacific region, especially in China, Japan, and South Korea, new energy vehicle production already accounts for more than 65% of the global total, directly driving the surge in demand for lightweight casting components.
Demand Characteristics of New Energy Vehicle Lightweight Casting
- Battery pack lightweighting: Electric vehicle battery packs account for 30%-40% of the vehicle's total weight. Battery pack casings, brackets and other components use lightweight materials such as aluminum alloy and magnesium alloy casting, which can reduce weight by 15%-25%.
- Chassis system integration: Integrated die-casting technology is replacing traditional multi-piece welding processes. Leading companies like Tesla have already achieved one-time molding of more than 70 parts, significantly reducing weight and improving production efficiency.
- Motor and control system lightweighting: Key components such as motor casings and control boxes use lightweight alloy casting, reducing weight while ensuring heat dissipation performance, improving overall vehicle energy efficiency.
Development Trends of Lightweight Casting Technology in Asia-Pacific Region
Automotive lightweight casting technology in the Asia-Pacific region is undergoing a transformation and upgrading from traditional processes to digital and intelligent directions. Casting enterprises in China, Japan, South Korea and other countries are increasing R&D investment to promote technological innovation in lightweight casting.
Key Technological Innovation Areas
In materials science, the application of high-performance aluminum alloys, magnesium alloys, and composite materials is becoming increasingly widespread. Japanese companies have developed ultra-high-strength aluminum alloys with tensile strength exceeding 500MPa, while maintaining good casting properties and toughness, which have been widely used in new energy vehicle body structural parts. Chinese casting companies have developed rare earth magnesium alloys, which are 30% lighter than aluminum alloys and 20% stronger, showing great application potential in electric vehicle components.
In terms of process technology, integrated die-casting technology has become an industry hotspot. A well-known new energy vehicle parts supplier in China has built the world's largest 6,000-ton integrated die-casting production line, which can form large body structural parts in one go, improving production efficiency by 80% and reducing costs by 30%. Meanwhile, advanced processes such as semi-solid casting and vacuum die-casting are also being rapidly promoted and applied in the Asia-Pacific region, significantly improving casting quality and performance.
Digital Transformation and Intelligent Manufacturing
Leading casting enterprises in the Asia-Pacific region are actively promoting digital transformation, introducing artificial intelligence, big data analysis, and Internet of Things technologies to achieve intelligent control and precise quality management of the casting process. A major casting company in South Korea has developed an intelligent casting system that reduces casting defects by 40% and improves production efficiency by 35% through real-time monitoring and data analysis.
Asia-Pacific Automotive Lightweight Casting Industry Chain Restructuring
With the rapid development of the new energy vehicle industry, the automotive lightweight casting industry chain in the Asia-Pacific region is undergoing profound restructuring, showing trends of regionalization, clustering, and specialization.
Regional Agglomeration Characteristics of the Industry Chain
The Asia-Pacific region has formed three major automotive lightweight casting industry clusters: the East Asian cluster centered in the Yangtze River Delta and Pearl River Delta regions of China, the Southeast Asian cluster represented by Thailand and Vietnam, and the South Asian cluster with growth points in India and Malaysia. These industry clusters have formed significant competitive advantages through complete industry chain support, abundant labor resources, and policy support.
Deep Integration and Vertical Integration of Supply Chain
New energy vehicle manufacturers are accelerating upstream extension through strategic investments and equity partnerships to strengthen control over the lightweight casting supply chain. A major new energy vehicle company in China has acquired three core casting enterprises to achieve self-containment of key components. Meanwhile, casting enterprises are also expanding downstream to provide one-stop solutions from material development, component design to system integration.
Analysis of Investment Opportunities in Asia-Pacific Automotive Lightweight Casting
With the rapid expansion of the Asia-Pacific automotive lightweight casting market, investment opportunities continue to emerge. Investors can focus on the following areas:
High-Growth Sub-sectors
- New energy vehicle integrated die-casting: Expected to have a compound annual growth rate of 35% from 2026 to 2030, making it the most promising investment area currently.
- Magnesium alloy lightweight casting: With material cost reduction and process maturity, the magnesium alloy casting market will experience explosive growth, with an expected annual compound growth rate exceeding 40%.
- Intelligent casting equipment: There is strong demand for automated and intelligent casting equipment, with the market expected to expand at a 25% annual compound growth rate.
Regional Investment Hotspots
China, as the largest automotive production and consumption market in the Asia-Pacific region, offers the richest investment opportunities in lightweight casting. Especially in the Yangtze River Delta and Pearl River Delta regions, there are complete industry chain support and policy support. The Southeast Asian region is becoming a new investment hotspot with cost advantages and free trade agreements. Thailand, Vietnam and other countries have introduced various preferential policies to attract casting industry investment.
Investment Risks and Challenges
Although the Asia-Pacific automotive lightweight casting market has broad prospects, investors should also pay attention to the following risk factors:
Technology Iteration Risks
Lightweight casting technology is updating and iterating rapidly, requiring companies to continuously invest in R&D, otherwise they face the risk of technological lag. Especially in emerging fields such as integrated die-casting and 3D printing casting, there are high technical barriers and large R&D investments, posing significant challenges for small and medium-sized enterprises.
Raw Material Price Fluctuations
Prices of raw materials such as aluminum alloys and magnesium alloys are greatly affected by international market supply and demand, and price fluctuations directly affect corporate profitability. Since 2026, affected by the global energy crisis and supply chain tensions, aluminum prices have fluctuated by more than 30%, bringing significant operational pressure to casting enterprises.
Stricter Environmental Policies
Environmental policies in Asia-Pacific countries are becoming increasingly strict, and the casting industry faces higher environmental requirements. China's "Technical Policy for Pollution Prevention and Control in the Casting Industry" sets higher standards for emissions, requiring companies to invest heavily in environmental facility upgrades, increasing operational costs.
Future Development Trends Outlook
Looking ahead, the Asia-Pacific automotive lightweight casting market will show the following development trends:
Acceleration of Green and Low-Carbon Transformation
Driven by carbon neutrality goals, green casting will become the mainstream of industry development. Using clean energy production, developing low-carbon emission processes, and improving resource utilization efficiency will become the core competitiveness of casting enterprises. By 2030, the market share of green casting in the Asia-Pacific region is expected to exceed 50%.
Deep Integration of Industry Chain
Automotive lightweight casting will deeply integrate with materials science, intelligent manufacturing, and digital technology, forming a new pattern of cross-industry collaborative innovation. Casting enterprises will no longer be limited to traditional manufacturing roles but will extend to high-value-added fields such as material development, design services, and system integration.
Regional Cooperation and Competition Coexist
Asia-Pacific countries will engage in deeper cooperation and competition in the field of automotive lightweight casting. On one hand, cooperation will be strengthened through regional trade agreements and technology exchanges; on the other hand, fierce competition will be conducted in high-end technologies and market share, forming a multi-level and diversified regional industrial structure.
Overall, driven by the vigorous development of the new energy vehicle industry, the Asia-Pacific automotive lightweight casting market is experiencing unprecedented development opportunities. Investors should grasp the historic opportunity of industry chain restructuring, focus on technological innovation, green development, and regional layout, while being alert to risk factors such as technology iteration, raw material price fluctuations, and stricter environmental policies, to maximize investment returns.